
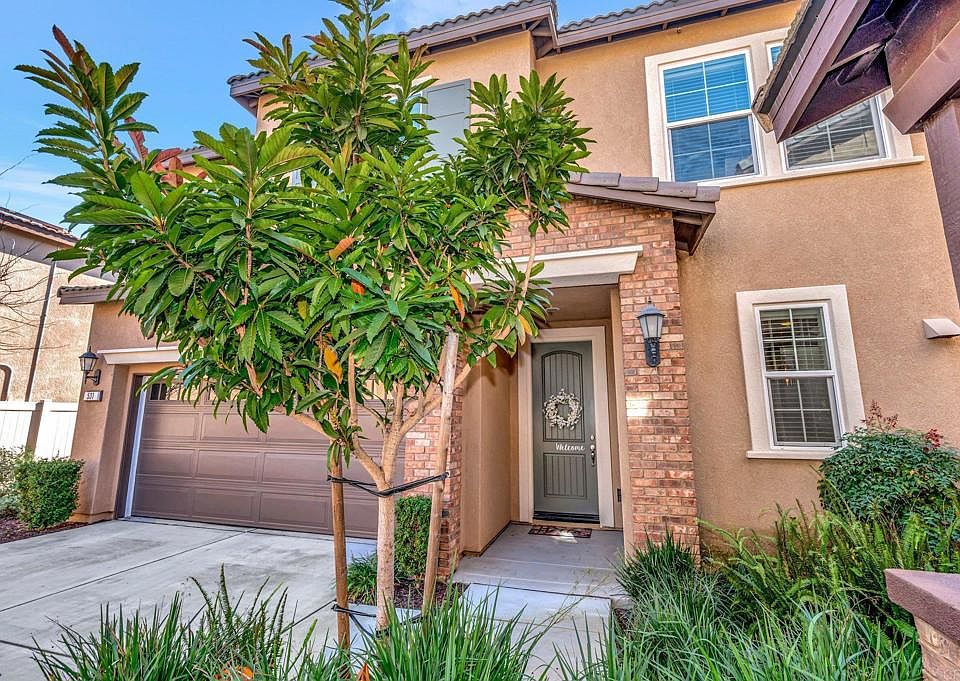
Sean and you will Beth McElhenny’s group of four has just purchased a good around three-rooms home in the Sydney’s northern something that they did not thought they might have the ability to manage having more ten years.
And as opposed to paying $six,800 thirty day period in the home loan repayments the couple, who work since the teachers, only pay half of you to number.
But he states some one eligible for the new design create work for
The new catch are, commercially they merely own 50 % of our house another 50 % of is owned by a great nonprofit that they may buy aside at any time.
The house is purchased as part of a provided equity strategy, in which the government otherwise nonprofit expenditures a fraction of a house and one otherwise couples is the owner of the remainder.
Such as for example strategies is actually broadening in dominance across Australian continent, and certainly will render a base right up towards housing marketplace having people that do not have the right out-of parental money. But they are it a solution to Australia’s homes crisis?
It’s institutionalising the bank regarding mum and you may dad for all of us one do not have the bank from mum and dad, claims Tim Buskens, leader from Hope Property, and that relies on traders for its system and you may whereby McElhenny purchased their household.
The brand new organization, like many shared collateral techniques, allows individuals to pick toward a house having a smaller put and potato chips during the a percentage of the rate so the visitors only has to make mortgage repayments to their cut.
Mostly thru person to person, Pledge Housing possess so far offered half dozen group to get good house as it introduced inside August, Buskin states. It has got a deeper a dozen recognized, and you will 85 for the waiting checklist, which is directed at key professionals particularly nurses, coaches and you will cleaners, that simply don’t secure a Questionnaire salary and can’t afford to live-in their communities.
Joey Moloney, an economics specialist during the Grattan Institute, believes eg techniques might help individuals who do not have use of adult money.
According to a recently available survey by the thinktank For each Capita, two-thirds from Australians trying to purchase a house accept it as true will simply be you can via a heredity off their moms and dads.
Nonprofit plans aim to help first homebuyers https://clickcashadvance.com/installment-loans-ms/houston exactly who usually do not count for the the lending company off mum and you may dad’ nonetheless have its limitations
But, according to him, it is simply one unit in the construction toolbox which should be restricted, or even it threats operating right up family pricing further.
Nonetheless, he says it must be an essential part of your own government government’s houses plan. Work guaranteed a system in the lead-around the past election, but it’s but really so you can materialise.
Per week the publishers look for four of the most interesting, humorous and you will innovative reads written by Guardian Australian continent and you will all of our worldwide acquaintances. Subscribe discovered it on your email every Monday morning
Privacy Observe: Updates may consist of information on charities, on the internet advertisements, and blogs financed by the external parties. For more information come across the Privacy. We explore Yahoo reCaptcha to protect the web site therefore the Bing Privacy policy and Terms of service implement.
Moloney says brand new system can be geared towards single people generating upwards so you’re able to $60,000 and you may partners generating up to $ninety,000 who if not getting closed out from the housing industry. He states it would be top directed into the anybody caught renting exactly who won’t if you don’t manage to pay a home loan prior to they retire, or anyone seeking to win back owning a home once a separation.
Sean McElhenny, thirty five, ended up being located in a two-room apartment together with his category of five. McElhenny claims it would was indeed too-late purchasing once they may spend the money for about three-rooms family they want.
Zero intentions to promote: the McElhenny family home, that they ordered with assistance from good nonprofit category. Photograph: Blake Clear-Wiggins/This new Guardian
In 10 to 15 years, the fresh students would have been looking at leaving household therefore we wouldn’t also need it after that, he states.
He states he could be perhaps not troubled by the reality the guy and you may Beth manage only secure fifty% of the cash in the event your home would be to be offered, considering it find it once the a stable family home on the second 2 decades rather good moneymaker.